Retail Software
 Distribution Software
 Retail Chain


Belated Return Due Date for AY 2026-27: Last Date, Late Fee & How to File

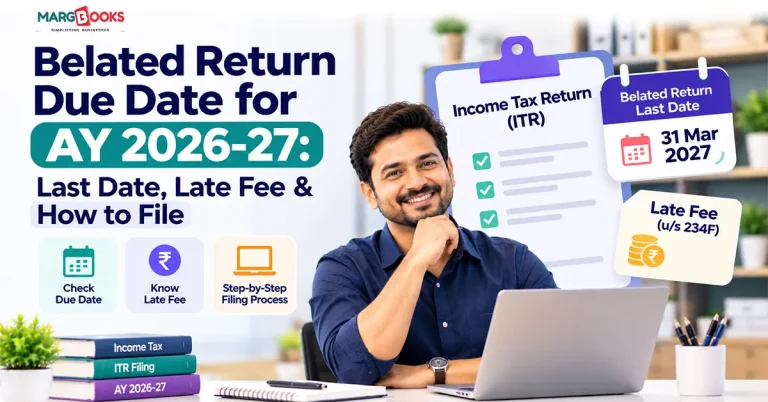
If your original ITR due date for AY 2026-27 has passed and you still have not filed, you can file a belated return. It does not matter whether you missed 31 July, 31 August, or another date that applied to your category. It happens more often than people admit. A job change, a missing Form 16, a busy quarter at the shop, or plain forgetting.
The good news is that you still have time. The belated return due date for AY 2026-27 (FY 2025-26) is 31 December 2026. You can file under Section 139(4) until then. You will pay a late fee and some interest, and you will lose a few benefits, but you will stay on the right side of the law. This post covers the date, what late filing costs, and how to file step by step.
What is the belated return due date for AY 2026-27?
The last date to file a belated return for AY 2026-27 is 31 December 2026, or the date the assessment is completed if that comes sooner. A belated return is a normal ITR filed after the original due date. A late fee of up to ₹5,000 under Section 234F applies, along with interest under Section 234A on any unpaid tax. After that, an updated return (ITR-U) may be available until 31 March 2031, subject to eligibility.
Return deadlines
Here are the details of the return deadlines-
| Return type | Section | Last date for AY 2026-27 | Main limit |
| Original return | 139(1) | 31 July 2026 for most individuals; 31 August, 21 November or 30 November for other categories (see below) | None |
| Belated return | 139(4) | 31 December 2026 | Late fee and interest; most losses cannot be carried forward |
| Revised return | 139(5) | 31 March 2027, or until assessment is completed if that comes first | Needs an original or belated return first |
| Updated return (ITR-U) | 139(8A) | 31 March 2031 | Extra tax of 25% to 70%; no refund |
The Income-tax Act, 2025 came into force on 1 April 2026, but returns for AY 2026-27 are still filed under the 1961 Act. The section numbers above are the ones to use.
What is a belated return?
It is simply your ITR filed late. Same form, same portal, same income details. The only difference is that you pick the filing type “After due date [139(4)]” instead of “Before due date [139(1)]”, and you pay for the delay.
Anyone who missed the original deadline can file one. That includes salaried employees, freelancers, traders, and business owners.
Original ITR due dates for AY 2026-27
Your belated window only starts once your own original deadline has passed, and that date depends on who you are.
- Salaried individuals and most non-audit cases (ITR-1, ITR-2): 31 July 2026
- Business and professional income without audit (ITR-3, ITR-4): 31 August 2026
- Companies and cases needing a tax audit: 21 November 2026 (the CBDT moved it from 31 October on 28 September 2026)
- Cases needing a transfer pricing report: 30 November 2026 (not covered by the extension)
The belated deadline of 31 December 2026 is the same for everyone.
What late filing costs you
Filing late is better than not filing, but it is not free.
Late fee under Section 234F: ₹5,000 if your total income is above ₹5 lakh. ₹1,000 if your total income is up to ₹5 lakh. Whether the fee applies at all also depends on whether you were legally required to file. Some people have to file even when their income is below the basic exemption limit.
Interest under Section 234A: You pay interest at 1% for every month or part of a month on the tax still unpaid after TDS and advance tax credits. It runs from the day after your original due date until the day you file, so filing sooner means less interest.
Loss carry-forward: This is the cost many people miss. In a belated return, you generally cannot carry forward losses, such as business losses or capital losses, to later years. Loss from house property is the exception. If you had a loss this year, filing late can cost you more than the ₹5,000 fee.
Refund interest: You can still claim a refund through a belated return. Under Section 244A, though, refund interest generally starts from the date you file the belated return, subject to the statutory conditions.
Some deductions and exemptions: A few tax benefits depend on filing by the original due date. Check with your CA if you claim anything beyond the standard deductions.
Belated, revised, and updated return: what is the difference?
People mix these up all the time. A belated return is for someone who never filed on time. A revised return is for someone who did file, original or belated, and then found a mistake or left something out. An updated return (ITR-U) is the last resort, for someone who missed even the belated deadline or wants to report extra income.
A belated return can be revised. An updated return cannot. And an updated return will not give you a refund, so do not treat it as a second chance to claim one.
How to file a belated return, step by step
- Log in to the income tax e-filing portal with your PAN and password.
- Go to e-File, then Income Tax Returns, then File Income Tax Return.
- Choose assessment year 2026-27 and the online mode.
- Select your status (individual, HUF, firm, and so on) and the correct ITR form.
- Under the reason for filing, choose Belated return u/s 139(4).
- Fill in your income, deductions, and tax paid. The pre-filled data comes from your AIS and Form 26AS, so check it against your own records.
- Pay any tax, interest, and late fees due through the portal. The tax computation shows these amounts.
- Submit, then e-verify using Aadhaar OTP, net banking, or a demat account. A return that is not verified within 30 days is treated as not filed.
Keep the acknowledgement. You will need it if you apply for a loan or a visa, or if the department sends a notice later.
Documents to keep ready
- PAN and Aadhaar
- Form 16 from your employer, or Form 16A for other TDS
- AIS and Form 26AS (to match TDS credits)
- Bank statements and interest certificates
- Capital gains statements, if you sold shares, mutual funds, or property
- For business owners: profit and loss account, balance sheet, and GST records
If you run a business, the TDS side matters too, since your vendors and employees depend on your filings for their own credit.
What if you miss 31 December 2026 as well?
You may still be able to file an updated return under Section 139(8A) until 31 March 2031, if you meet the eligibility conditions. It comes with extra tax of 25% to 70% on top of the tax and interest due, depending on how late you are. You cannot use it to claim a refund or increase one, to reduce the tax you declared earlier, to show a bigger loss, or to file a second updated return for the same year. If you reach this stage, talk to a CA before filing.
Conclusion
The belated return due date for AY 2026-27 is 31 December 2026. If you have not filed, do it soon. The late fee does not change, but interest keeps running on any tax you owe, and every week you wait is a week closer to losing the option altogether.
Most late filers are not trying to dodge anything. They just cannot find the numbers in time. For a business, that usually means income and expenses scattered across bills, bank statements, and a notebook.
Keeping everything in one place changes this. With MargBooks cloud accounting software, your sales, purchases, and ledgers are recorded as you go, so the figures your CA needs at year-end are already there. Billing software and GST billing keep your invoices tied to your accounts, and the financial year closing feature helps you wrap up the books cleanly each March. You can also check your numbers on the go with the MargBooks mobile app, and the reminders help you stay ahead of tax dates.
Tax rules and dates change. This post is for general information and is not tax advice. Confirm current deadlines on the income tax e-filing portal or with a chartered accountant.
FAQs
Q1. What is the last date for belated return for AY 2026-27?
31 December 2026, under Section 139(4). If assessment is completed before that date, the window closes earlier.
Q2. Can I file ITR after 31 December 2026?
Only through an updated return (ITR-U), if you are eligible, until 31 March 2031. It attracts extra tax and does not allow refunds.
Q3. What is the penalty for filing a belated return?
A late fee of ₹5,000 under Section 234F, or ₹1,000 if total income is up to ₹5 lakh, plus 1% monthly interest under Section 234A on any tax due.
Q4. Can I revise a belated return?
Yes. A belated return can be revised if you find an error, but only until 31 March 2027, or until assessment is completed if that comes first.
Q5. Can I claim a refund in a belated return?
Yes, you can. Refund interest, however, runs from the date you file.
Q6. Can I carry forward losses if I file late?
Generally no, except for loss from house property. This is the highest hidden cost of filing after the due date.
Q7. Is a belated return the same as an updated return?
No. A belated return is for missing the original due date and can be filed until 31 December 2026. An updated return comes after that, until 31 March 2031, and costs more.
Q8. Has the ITR deadline for audit cases been extended for AY 2026-27?
Yes. On 28 September 2026, the CBDT moved the return date for audit cases from 31 October to 21 November 2026. The tax audit report date moved from 30 September to 21 October 2026. Transfer pricing cases still have a due date of 30 November 2026.
Aman Kannojia is the Digital Team Lead at MargBooks. He started out as an SEO Specialist and never lost his love for words. With 5 years of experience across banking, SaaS, and finance, both domestic and international, he brings strategy, leadership, and storytelling together. He doesn’t just manage a team, he builds one that creates.